Key Takeaways
- The lowest premium is not always the lowest-cost option over a full year.
- Network rules can affect both your choice of dentist and what you pay for care.
- Compare preventive, basic, major, and orthodontic benefits separately.
- Deductibles, annual maximums, and exclusions can substantially affect plan value.
- A side-by-side checklist makes it easier to choose coverage based on real needs.
Comparing dental plans in 2026 starts with more than choosing the smallest monthly premium. Whether coverage comes through an employer, an individual policy, or a public-sector benefit option, it helps to review government dental insurance alongside other available choices before enrolling.
A plan that looks inexpensive each month may have a deductible, a limited network, or an annual payment limit that makes it less useful when treatment is needed. The strongest choice is usually the one that fits your expected care, household budget, and preferred dental providers.
Why Dental Plan Comparison Matters
Dental benefits often divide services into categories and pay different amounts for each one. A person who expects only examinations and cleanings may value low premiums and strong preventive coverage. Someone expecting crowns, root canal treatment, dentures, or orthodontic care may need to focus more closely on benefit percentages and annual limits.
Two plans can have similar premiums but create very different bills after a filling or crown. Comparing the full design of each plan helps prevent surprises and makes it easier to budget for both routine and unexpected care.
Start With Expected Care Needs
Before reading plan brochures, think about the dental care each household member is likely to need during the coming year. Review recent dental bills, upcoming appointments, and any treatment your dentist has discussed. If treatment is already planned, ask the dental office for a written estimate and, when available, the procedure codes.
Useful questions include:
- How often will each person need exams, cleanings, or X-rays?
- Are fillings, periodontal treatment, extractions, or specialist visits likely?
- Could anyone need a crown, bridge, root canal, implant, or dentures?
- Will a child or teenager need braces or retainers?
- Is keeping a current dentist important?
The American Dental Association offers practical explanations of deductibles, annual limits, coinsurance, exclusions, and other factors to weigh when comparing dental plans. Those terms are easier to evaluate when connected to your own likely treatment.
Compare the Full Cost
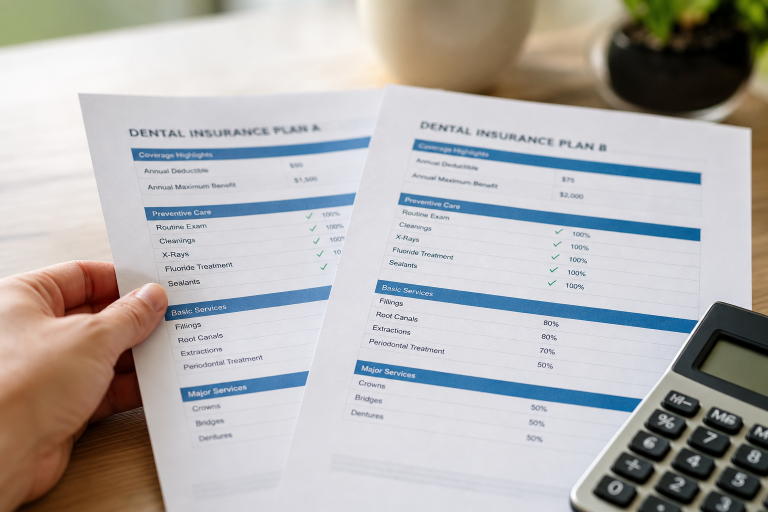
Premiums matter, but they are only one part of the cost. For every plan, identify the monthly or paycheck premium, annual deductible, copayments or coinsurance, annual maximum, out-of-network rules, and estimated cost of planned services.
Estimated yearly cost = premiums + expected out-of-pocket expenses − expected plan payments.
Run the calculation under three situations: routine care only, moderate treatment such as a filling or gum care, and major treatment such as a crown or root canal. This approach does not predict every expense, but it shows how plan costs can change when care needs increase.
Check the Provider Network
In-network dentists have an agreement with the plan, while out-of-network dentists may charge differently, which may result in higher patient costs. Do not assume a dentist participates just because they accept the insurer’s name. Confirm participation in the exact plan you are considering, preferably through both the plan directory and the dental office.
Also, check whether nearby pediatric dentists, endodontists, oral surgeons, periodontists, and emergency providers participate. A smaller network may offer favorable contracted costs, but it can limit provider choice. Recheck network status before starting expensive treatment because participation can change.
Review Covered Benefits and Limits
Compare each service category individually. Preventive services can include exams, cleanings, and X-rays. Basic services may include fillings, simple extractions, and certain gum treatments. Major services may include crowns, bridges, dentures, root canals, and, depending on the plan, implants. Orthodontic benefits may have separate age rules, percentage limits, or lifetime maximums.
Read the benefit document for frequency limits, such as how often cleanings or X-rays are covered. Also look for pre-existing condition exclusions, missing-tooth clauses, and least-expensive-treatment provisions. A least-expensive-treatment rule may limit what the plan pays when more than one clinically acceptable treatment option is available.
Account for Family and Retirement Changes
Household needs can shift quickly. Children may need orthodontic evaluations, adults may need restorative treatment, and retirees may need to replace employer-sponsored coverage. Check dependent eligibility rules, age limits, and what happens if a family member changes jobs, moves, or retires.
For Marketplace shoppers, dental coverage is handled differently for adults and children. The federal Marketplace explains that dental coverage must be available for children. In contrast, adult dental coverage is not required as an essential health benefit, so it is important to carefully compare the available options.
Use a Simple Comparison Checklist
Create a list for Plan A, Plan B, and Plan C. Under each plan, write down:
- Monthly premium and annual premium total
- Individual and family deductible
- Annual maximum and any orthodontic lifetime maximum
- Preventive, basic, major, and orthodontic coverage details
- Frequency limits and major exclusions
- Whether your preferred dentist and needed specialists are in network
- Your estimated cost under routine, moderate, and major-treatment scenarios
Common Questions About Dental Plans
Is the cheapest dental plan usually the best choice?
Not necessarily. A lower premium can be valuable for someone expecting limited care, but it may be paired with higher cost sharing, fewer providers, or lower benefit limits. Compare the projected yearly total, not only the premium.
Should I choose a plan with a large provider network?
A broad network can be especially useful if you want to keep a current dentist, travel frequently, live in an area with fewer providers, or anticipate specialist care. Still, network size is only one factor. Confirm the providers you are most likely to use.
What should I check before scheduled treatment?
- Confirm that the dentist is in-network for your specific plan.
- Verify that the planned procedure is covered.
- Check whether a frequency limit applies.
- Find out how much of the annual maximum remains.
- Request a pre-treatment estimate from the dental office when appropriate.
Final Thoughts
A smart dental plan comparison begins with your likely care needs, not the premium alone. Start by reviewing provider networks to confirm your dentist participates, then review covered services for both preventive and major procedures. Check annual benefit limits, since these caps determine how much the plan will pay before you’re responsible for the rest. Review exclusions and expected out-of-pocket costs, including deductibles and coinsurance. Comparing these details, rather than focusing on the premium price alone, helps you choose a plan with a clearer understanding of what it may actually provide in 2026.